Dave Shula Returns as President of Shula's Restaurant Group
Dave Shula rejoins Shula's Restaurant Group as president, leading growth into Palm Beach Gardens and a 2027 Thomasville, Georgia expansion.
News
Sep 23, 2026
Dave Shula rejoins Shula's Restaurant Group as president, leading growth into Palm Beach Gardens and a 2027 Thomasville, Georgia expansion.
Sep 23, 2026
McDonald's commits $8.5 billion through 2036 to modernize restaurants, boost cash flow by $100,000 per store, and grow chicken and beverage sales.
Sep 23, 2026
WKS Restaurant Group promotes Jay Spongberg to president and COO after he helped grow the company from 65 to 382 restaurants over 16 years.
Sep 23, 2026

Smokey Mo's BBQ names Von Dawson, a Dine Brands veteran, as VP of Franchise Development to lead its Texas expansion strategy.
Sep 23, 2026
Meritage Hospitality's Chapter 11 filing pulls 5% of Wendy's U.S. stores into bankruptcy, exposing cracks in franchising's bigger-is-safer bet.
Sep 21, 2026
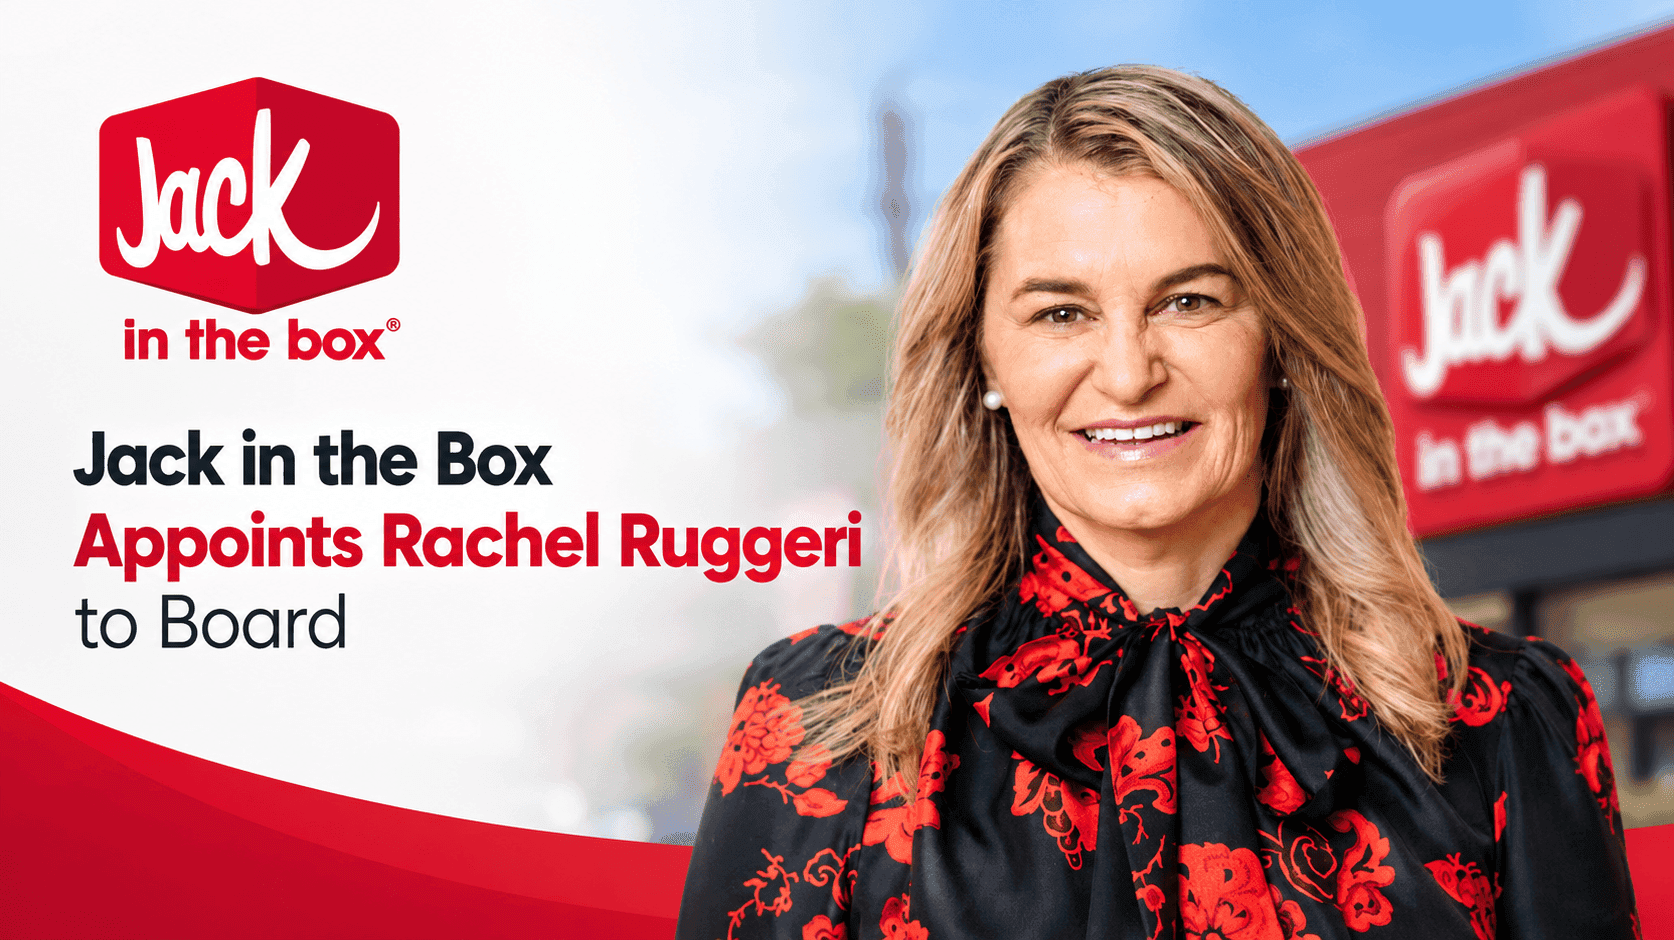
Jack in the Box names Rachel Ruggeri to its board as Michael Murphy retires, amid a CEO transition and deal with investor GreenWood.
Sep 21, 2026
Improve restaurant Google Maps rankings by optimizing your business profile, selecting accurate categories, gathering reviews, adding photos, and strengthening local relevance signals.
Sep 21, 2026
Restaurant inventory tracking helps owners monitor stock, control food costs, reduce waste, improve purchasing, and make informed operational decisions.
Sep 21, 2026
Restaurant owners can significantly reduce restaurant costs by leveraging technology across inventory, labor, procurement, forecasting, and administrative operations for better profit margins.
Sep 18, 2026
Understand how to forecast restaurant revenue and expenses with methods for sales projection, cost scaling, fixed-cost planning, and risk buffering.
Sep 18, 2026

Unlock Exclusive Access To Webinars, Events, And The Latest News For Free!
Recovery remains uneven as consumer confidence rises amid rising costs, testing profitability across markets.

Photo by Alex Haney
Across the third quarter, the patchwork narrative of the restaurant world softened into a more hopeful rhythm. Restaurant sales and traffic edged higher than in the harshest earlier quarters, offering a gentle reassurance to operators who learned to listen for subtle shifts in footfall and appetite. Yet amid the improving tempo, a soft hum of caveats lingered: consumer confidence rose by 11% in October, the strongest climb since March 2021, an encouraging data point that hints at demand returning to the table. In the background, New York City remained a barometer of caution, where the city’s dense dining scene carried its own stubborn gravity. The gains, in short, feel like a quiet note in a larger score: hopeful, but not definitive, and never universal.
Yet the gains are not uniform across markets or concepts, and closures and bankruptcies continue to punctuate headlines.
Within New York City, the summer letdown left a measurable scar. The NYC Hospitality Alliance reports that 72% of restaurants saw sales slip between June and August, while only 5% posted gains and 22% stayed level year over year. For those with declines, the losses clustered: 1–10% in 43% of cases, 11–20% in 29%, 21–30% in 24%, and more than 31% in 4%. That pattern underpins NYC’s darker mood: 33% of operators anticipate a difficult fall, 26% are uncertain, and 41% remain hopeful.
These local dynamics mirror a broader market where optimism travels unevenly.
Beyond New York, the pressure walls in many markets are reinforced by labor costs, rents, and regulatory frictions that operators say constrain growth. The NYC Hospitality Alliance survey highlights labor costs as the top concern (53%), followed by insufficient customer traffic (45%), a restrictive regulatory environment (39%), high commercial rents (36%), inflation (32%), and rising insurance rates (31%). These headwinds help explain why profitability remains elusive for many even as sentiment improves. In nearby Massachusetts, the same pressures ripple through a state economy projected to generate about $32.6 billion this year, yet still facing foot-traffic headwinds and rising costs. Stephen Clark, MRA president and CEO, warned: “Elevated costs and inflationary pressures continue to make operating a restaurant challenging.” This backdrop helps explain the uneven path to recovery.

Macro frame shapes every dinner rush and every labor hour. Even as optimism grows, the industry learns to live with cost pressure, regulatory frictions, and the stubborn realities of market-by-marketperformance.
Industry data suggest a bifurcated path to recovery. The 2024 Toast Voice of the Restaurant Industry survey found that 63% of operators reported higher profits than the previous year, while 4% saw profits decline and 33% reported flat results, underscoring growing disparities by region, concept, and market conditions. Hudson Riehle, research chief at the National Restaurant Association, attributed the divergence to “macro differences in regions, states, and metro areas,” noting that operating costs and occupancy, utility costs, and other factors can vary widely. He further warned that fragmentation is likely to intensify: “Looking ahead this year and beyond, that fragmentation of the industry overall will continue to grow.” These observations illustrate that even as averages improve, winners and losers emerge from local conditions and strategic choices.
Toast’s 2025 Voice of the Restaurant Industry survey reinforces a pragmatic tilt toward profitability and resilience, with operators leaning into technology, menu pricing, and guest experience rather than sweeping reductions in labor or hours.

Practical takeaway – A widening gap between those who invest in digital tools, price discipline, and supplier renegotiations and those who struggle to maintain margins. The path to sustainable profitability is increasingly driven by local decision-making and deft execution, not a single national playbook.
Voices from the frontline frame the tension between glow and gloom. Andrew Rigie, executive director of the NYC Hospitality Alliance, sounded the alarm: "Declining sales, too few customers, and high operating expenses are a warning sign that many of our city’s restaurants and bars are struggling." Massachusetts leaders echo similar concerns: Stephen Clark emphasizes that elevated costs and inflationary pressures are squeezing margins, even as households feel the impact of inflation. These operational realities are mirrored in the broader industry dialogue, where regional disparities translate into divergent outcomes for individual restaurants.

In this moment, a shared caution links policy, finance, and hospitality: costs bite, demand fluctuates, but the human rhythm of dining, shared tables, slow conversations, little luxuries, persists as a core signal of resilience.
Outcomes, timelines, and growing debt – From a policy and financing perspective, the outlook remains unsettled. In Massachusetts, lower traffic and higher costs translate into profitability challenges, with 40% of full-service establishments reporting lower profits than last year and almost 60% carrying pandemic-era debt. On the financing side, Toast’s disclosures through 2024 and into 2025 reveal a company expanding locations and profitability as macro conditions stay volatile. The firm’s fourth-quarter and full-year 2024 results highlighted a record pace of new locations and meaningful gains in recurring gross profit, while 2025 results point to continued growth and stronger margins. In February 2026, Toast reported that 2025 was a strong year, with a record number of net locations added and improved profitability metrics, reflecting the company’s role as a technology backbone for a sector facing cost pressures and shifting demand.

Broader context and remaining questions – The industry navigates a crowded field of factors, regional economic health, wage trends, supply chain resilience, and evolving guest behavior. The 2025 Toast data illustrate resilience, with nearly half of operators indicating they would consider raising menu prices if inflation persists, and many leaning into price optimization, supplier renegotiations, and analytics to protect margins. Yet profits remain vulnerable to policy shifts and macro shocks. The industry’s fragmentation means that the path forward will be uneven, with variation across markets and concepts. As the landscape evolves, operators, policymakers, and suppliers will balance inflation against strategies that sustain employment and dining access.
Implications and a cautious path forward – The convergence of rising confidence in some measures with persistent cost pressures in others suggests a cautious but real path to stabilization for the restaurant sector. Policy makers are urged to consider targeted supports that alleviate operating costs and regulatory friction without expanding the cost base for operators. For restaurant operators, the data reinforce the value of focusing on profitability through pricing discipline, supplier management, and productivity improvements, while preserving the workforce and guest experience as core competitive advantages. The industry’s trajectory, dense with regional variation, is unlikely to follow a single script, but the underlying signals point to a sector that can chart a sustainable course if cost inflation is brought to more manageable levels and foot traffic remains resilient across key markets.

Closing note: in the embrace of a cautious recovery, comfort and steady hospitality carry the day. When costs ease and guests return in numbers, the quiet resilience of dining rooms becomes a living reminder that warmth, routine, and a well-tended guest experience are the true anchors of a season that will still take time to fully mend.